ChainLink Cycles
Case exhibits
5 exhibits for this case
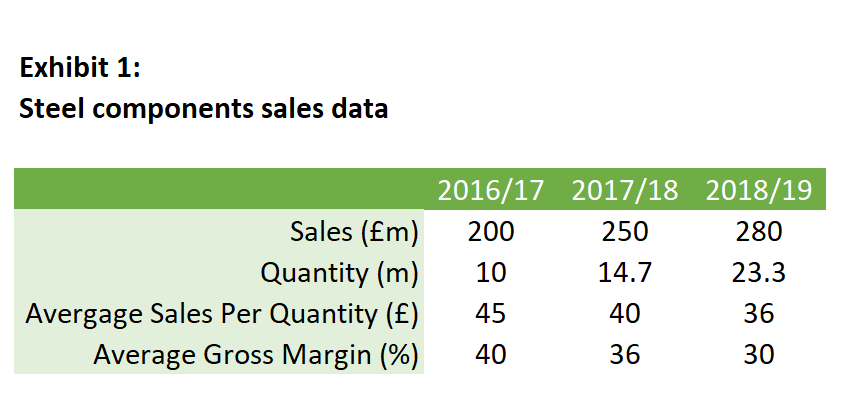
Exhibit 1
Identify the Problem
The candidate should make inquiries sufficient to receive the following information pertaining to various sections of ChainLink's value chain.
Previously, ChainLink has sourced the metal for its steel components domestically. However, recent changes in environmental legislation have led to a significant uptick in domestic steel prices. By switching to purchasing from foreign suppliers, ChainLink can save 30% of the raw material costs for its steel range. We assume that this issue off supplier pricing in the only significant driver of outlay on steel and that the amount spent on steel by Chainlink will not vary with sales quantity. ChainLink offers free shipping on all orders and finds this to be essential to be competitive in an industry where free shipping is the norm. Recently, though, shipping costs have grown much more rapidly than sales. Since components are heavy, shipping costs are high, and it has been established that these costs eliminate any positive profit for components with a gross profit margin of below 20%.
The candidate should establish the following root causes for the reduction in gross profit margin:
- Increasing sales of generic steel components with low gross profit margin
- Increase in raw material costs for steel component manufacture
- Increased competition in advanced carbon fibre component manufacture leading to significant price reductions.
Solutions
The candidate should be able to supply solutions touching on the following key points. They should be prompted to provide pros and cons of the different aspects if they do not do so immediately.
- Change the range of steel components offered to move away from low-margin generic items and to a higher proportion of own-design components. Specifically, items from this range priced below or equal to £10 do not contribute to profit and should be eliminated.
Gross profits will be increased as a function of removing low margin products. One issue might be a reduction in cross-selling of high-value items to customers initially interested in generic components. - Cease production of advanced carbon-fibre components. This move will increase profits. However, the company's overall brand might be damaged by the discontinuation of a premium product which it was well known for. Thus, it might be found that the existence of the advanced line had been boosting sales of steel components via a "halo effect". Any required staff layoffs could also damage the brand.
- Switch to a foreign steel supplier. This will result in the stated 30% saving in steel prices. However, the longer distance might make supply more vulnerable to disruption and would possibly make it harder to vary production at short notice. Adopting a new supplier might also risk problems with quality.
Projection
Now we need to provide the projection required by ChainLink.
Start with sales:
From last year, we reduce sales by £70m with the discontinuation of the carbon fibre range.
We further reduce sales with the move away from low-cost generic steel components. Removing all products below a sales price of £10 will generate a reduction of 25% in the value of steel component sales. That is another £70m reduction.
Thus, total sales will be £210m
Now gross profit margin:
Steel components under £10 - N/A
Steel components at £11- 30
Previous sales= 30% of 280 = £84m
Previous gross profit contribution = 20% of 84 = £16.8m
Steel components at £31-50
Previous sales = 20% of 280 = £56m
Previous gross profit contribution = 25% of 56 = £14m
Steel components at £51-100
Previous sales = 15% of 280 = £42m
Previous gross profit contribution = 30% of = £12.6m
Steel components at £100+
Previous sales = 10% of 280 = £28m
Previous gross profit contribution = 40% of = £11.2m
Reduction in steel costs of 30% adds 30% of 98 = £29.4m to profits
Therefore, total gross profit = 16.8 + 14 + 12.6 + 11.2 + 29.4 = £84m
Final Recommendation
The candidate should synthesise their quantitative and qualitative analyses to provide a unified client recommendation to ChainLink.
Two actions can improve gross profit margin.
- Change the mix of products sold
- Changing steel supplier
Recommendations are thus:
- Stop selling items priced at or below £10
- Cease production of carbon fibre range entirely
- Change steel supplier
With these measures taken, we would expect sales of £210 and a gross profit of £84m over the next year.